Wheat Market Update - 12th October 2026

| Instrument | Prior wk close (2 Oct) | Reporting wk close (9 Oct) | Change |
|---|---|---|---|
| ICE UK feed wheat — front month (Nov-26) | £206.25/t | £206.00/t | −£0.25 (−0.1%) |
| ICE UK feed wheat — Nov-26 | £206.25/t | £206.00/t | −£0.25 (−0.1%) |
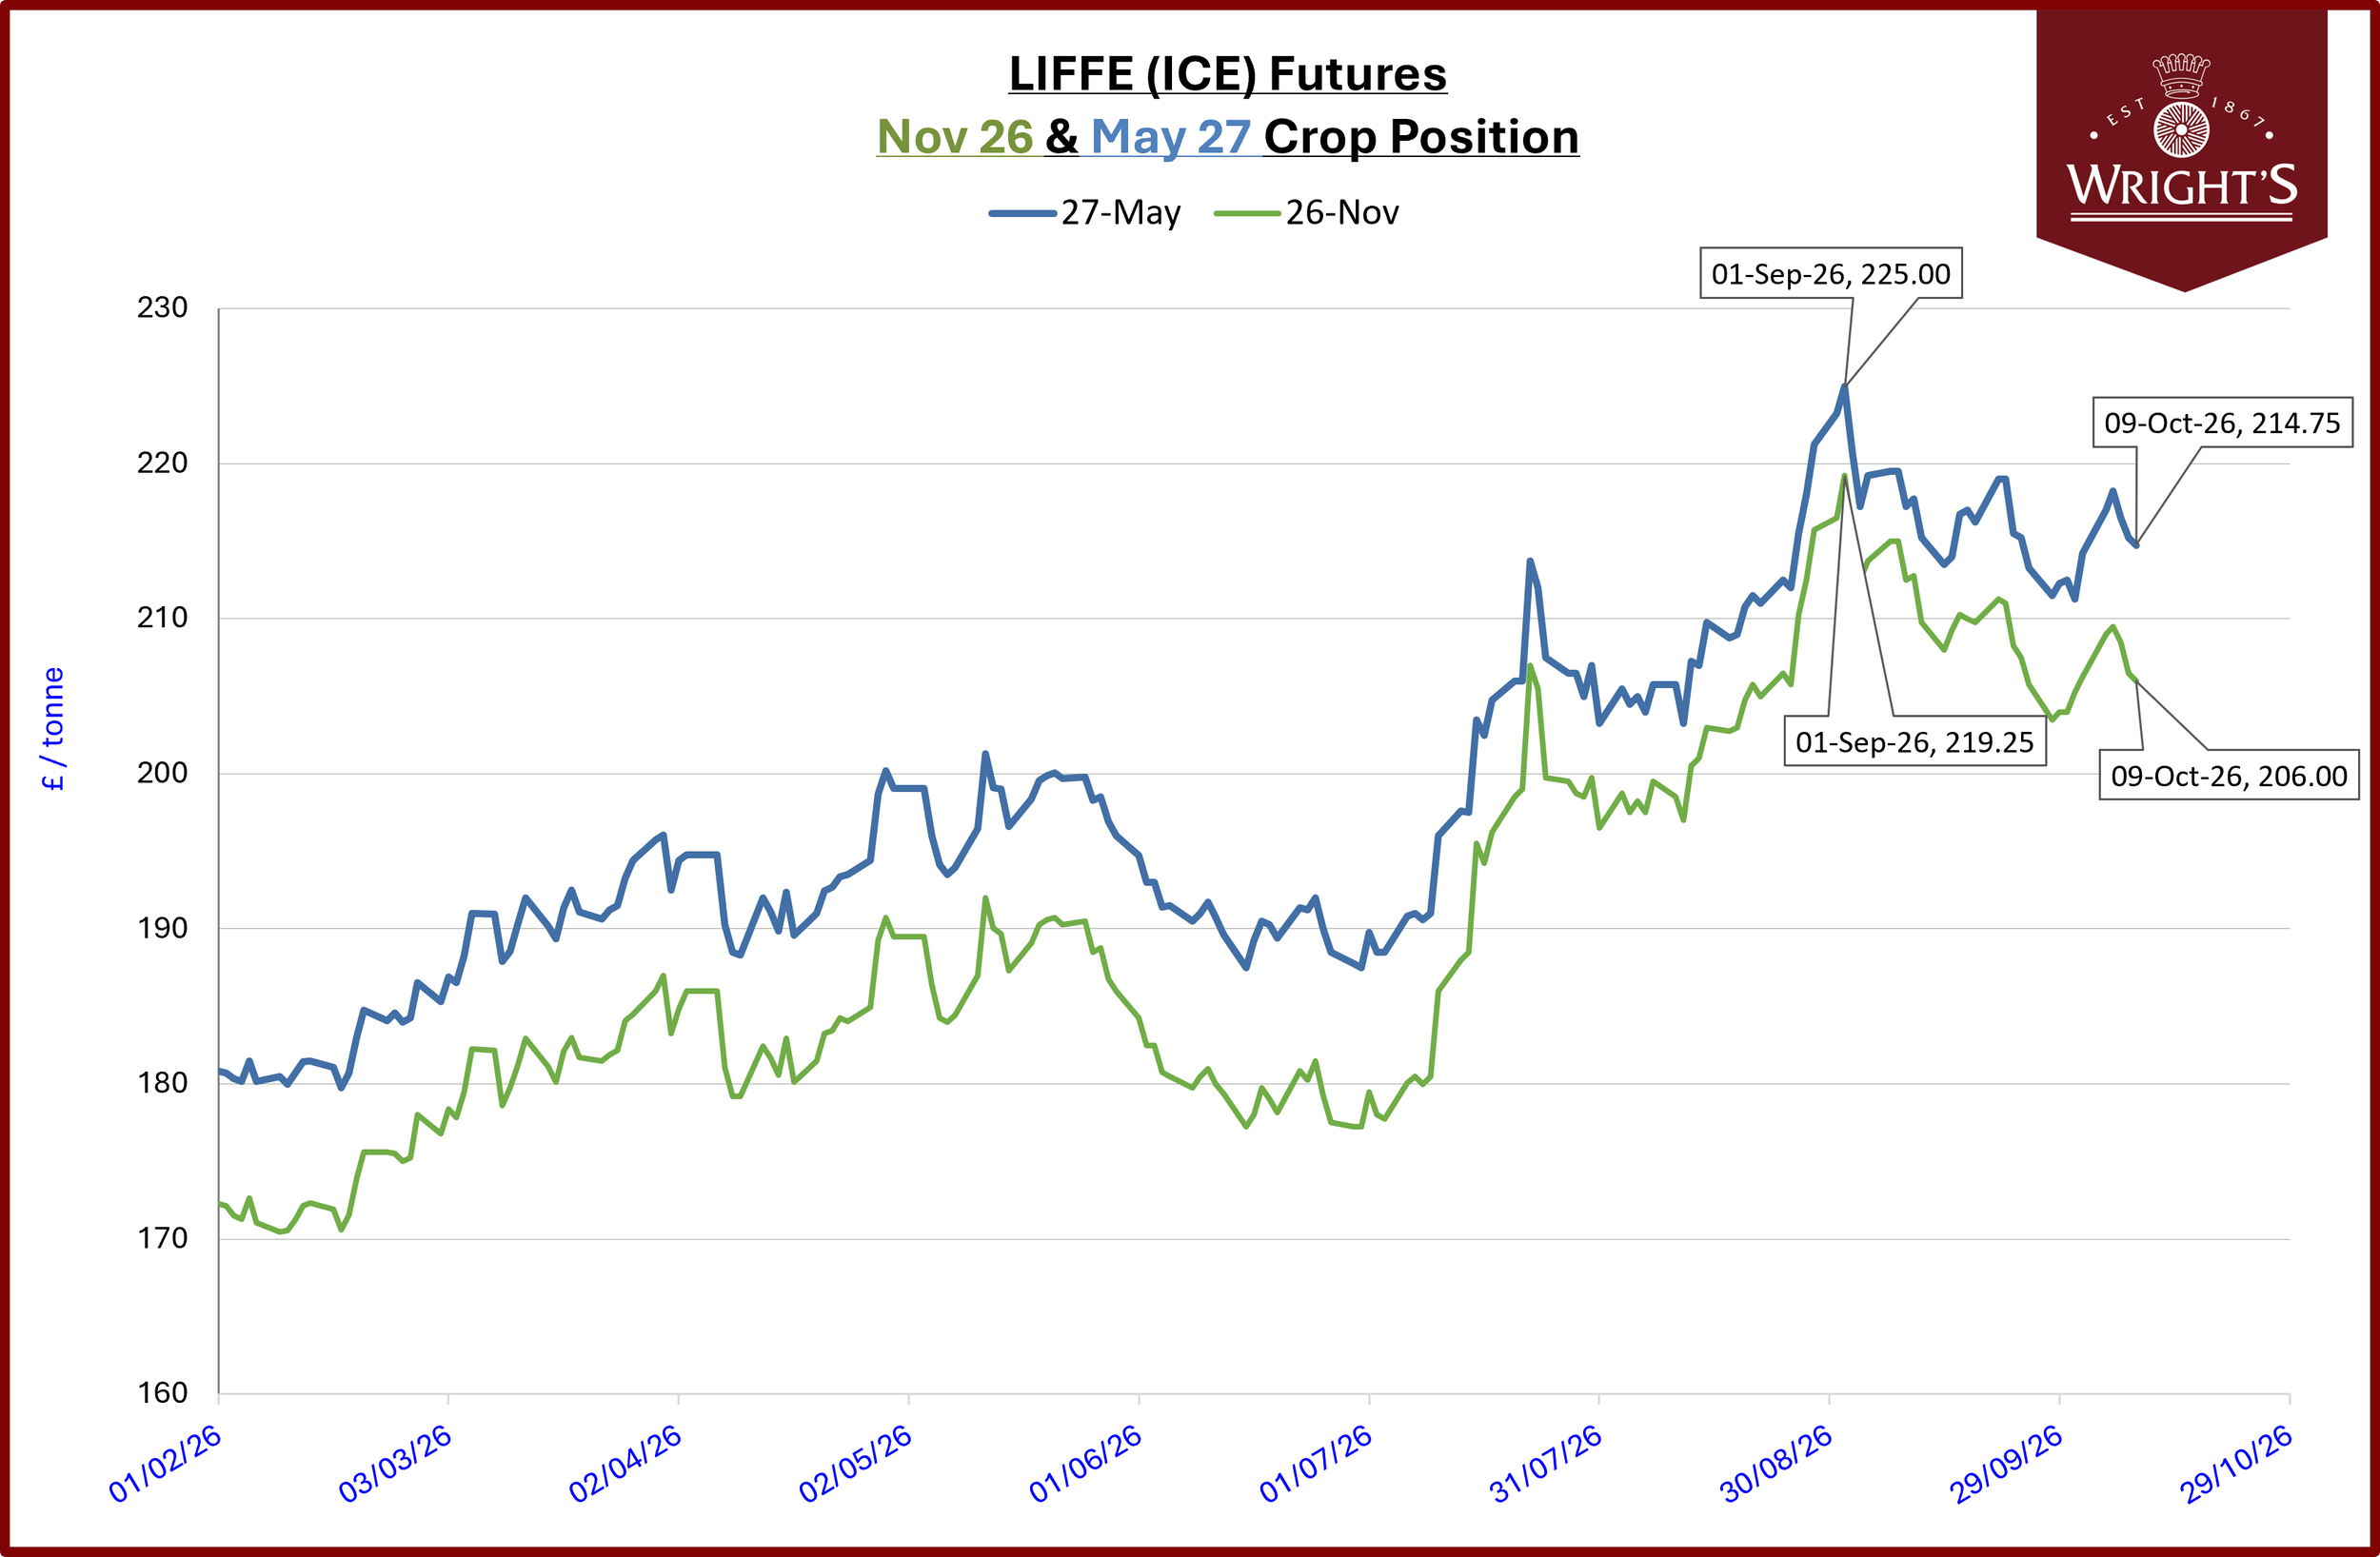
| ICE UK feed wheat — May-27 | £214.25/t | £214.75/t | +£0.50 (+0.2%) |
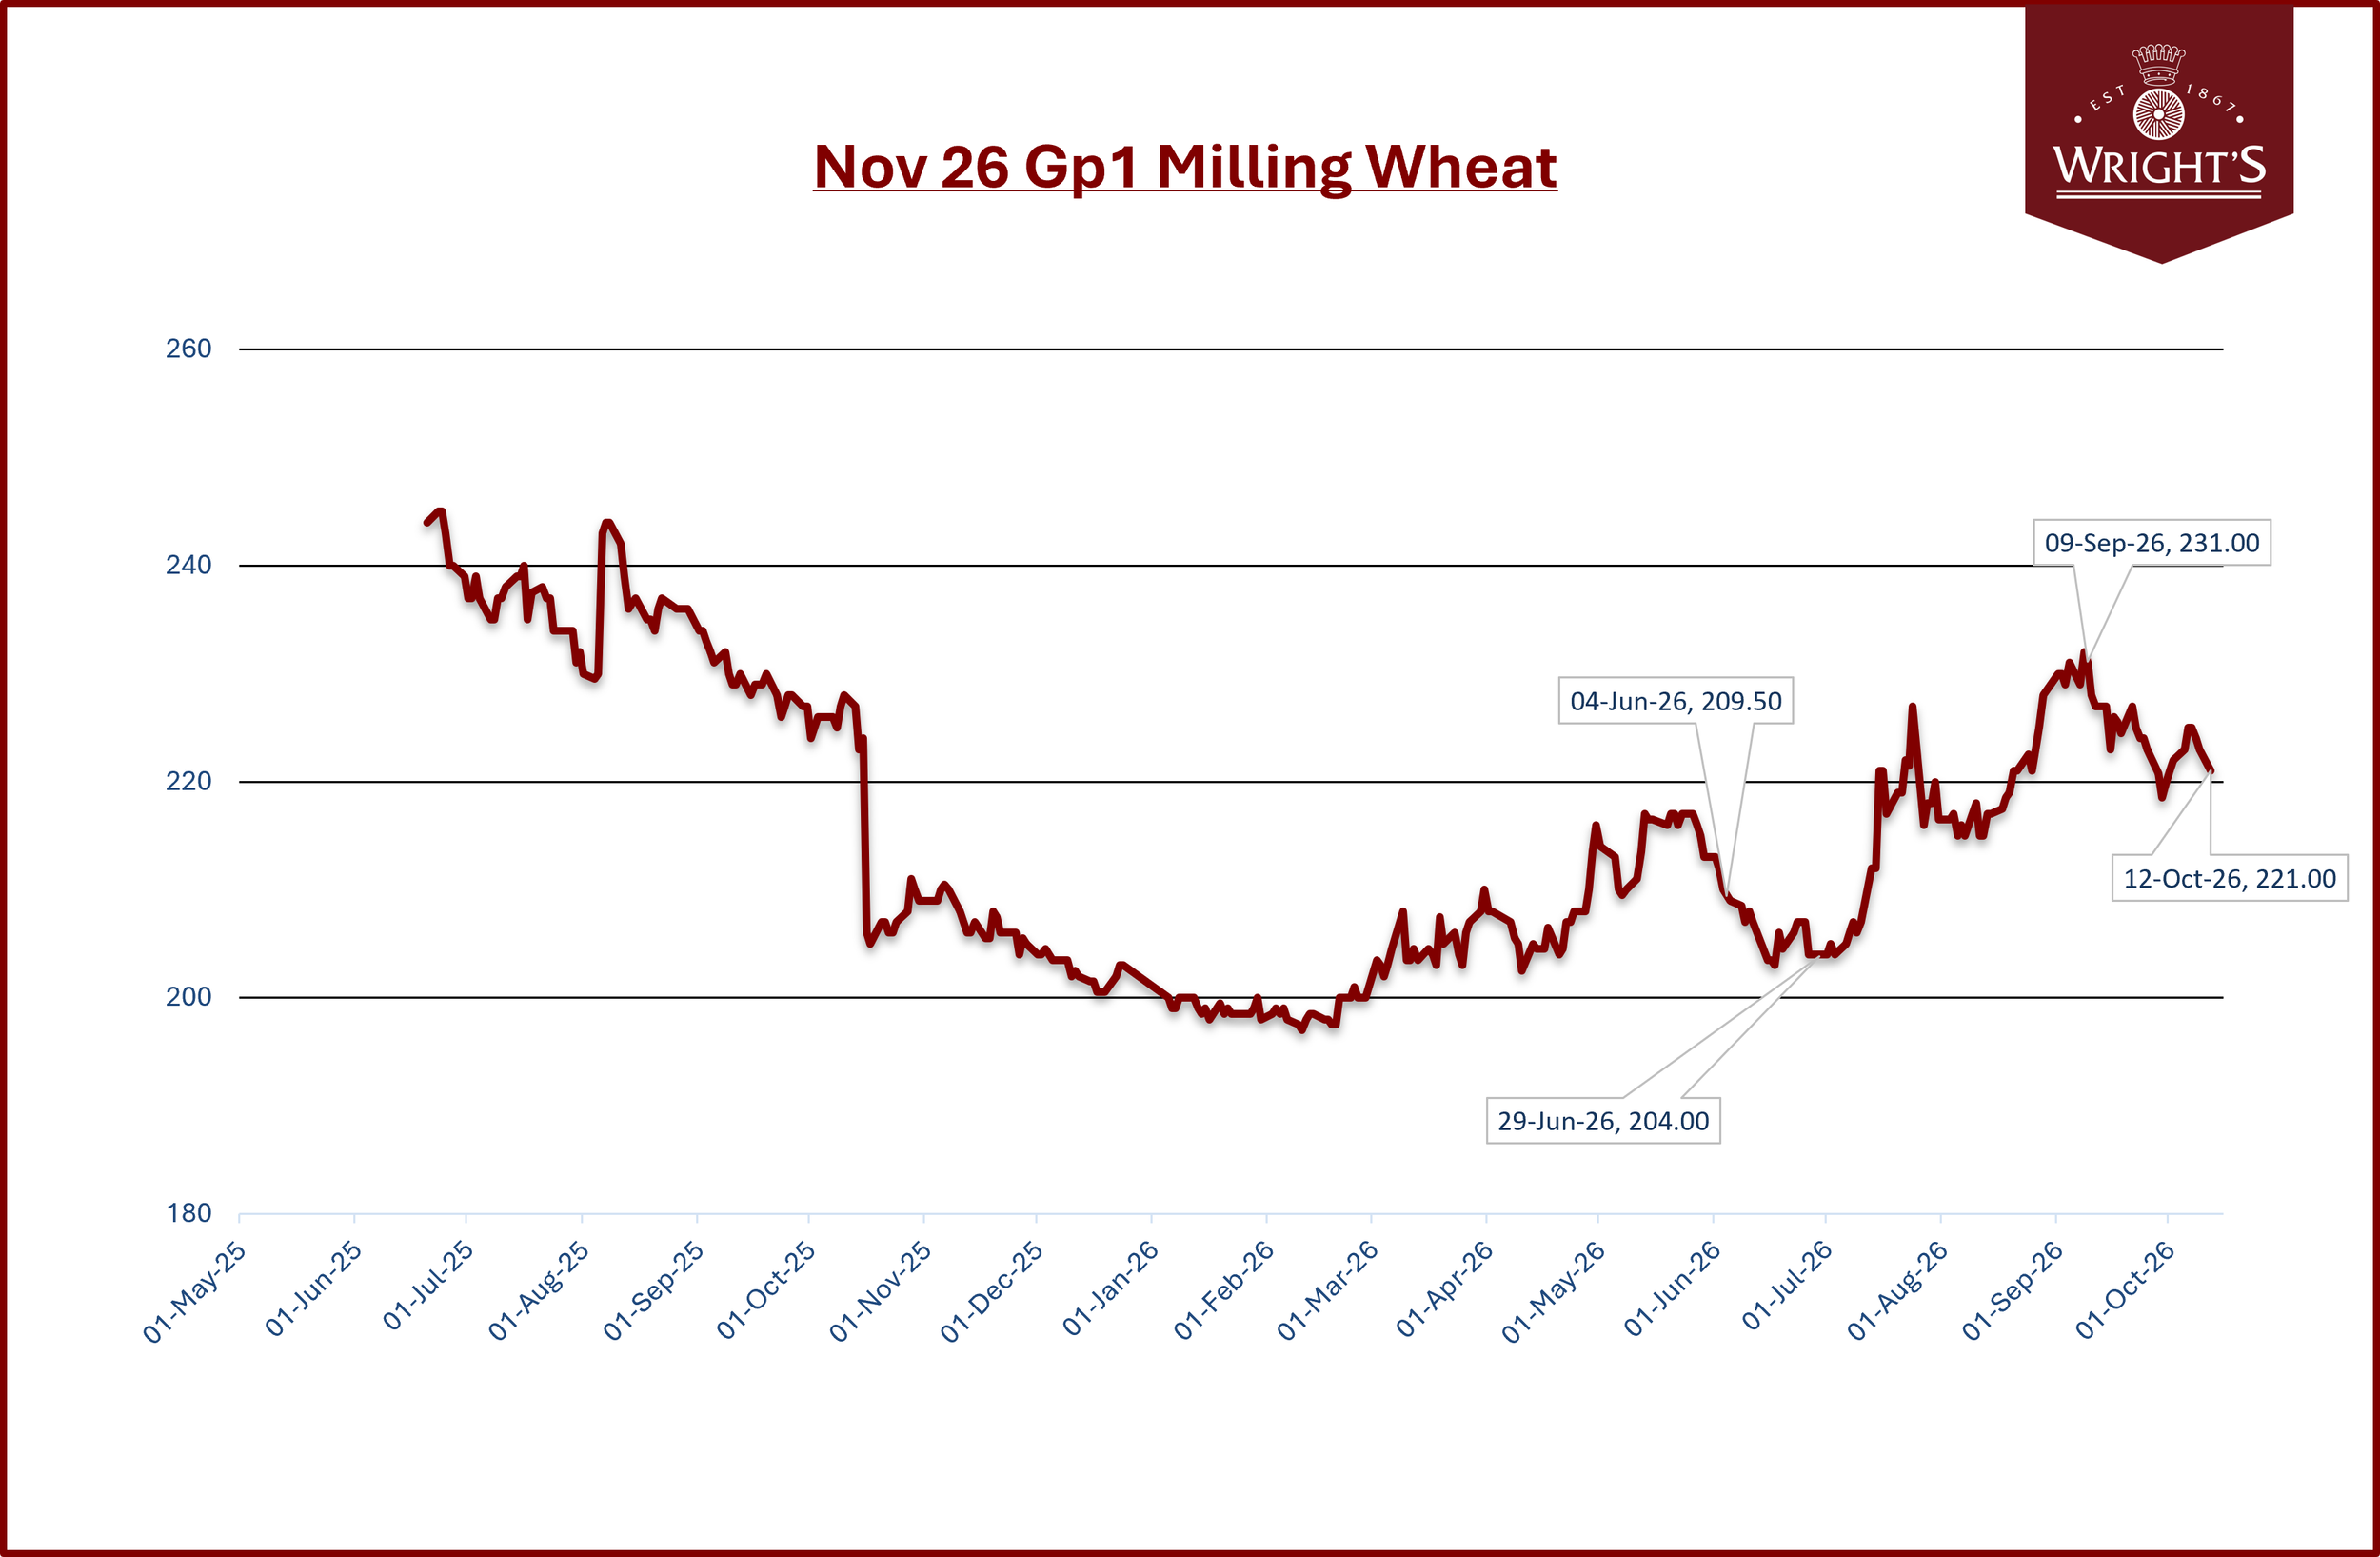
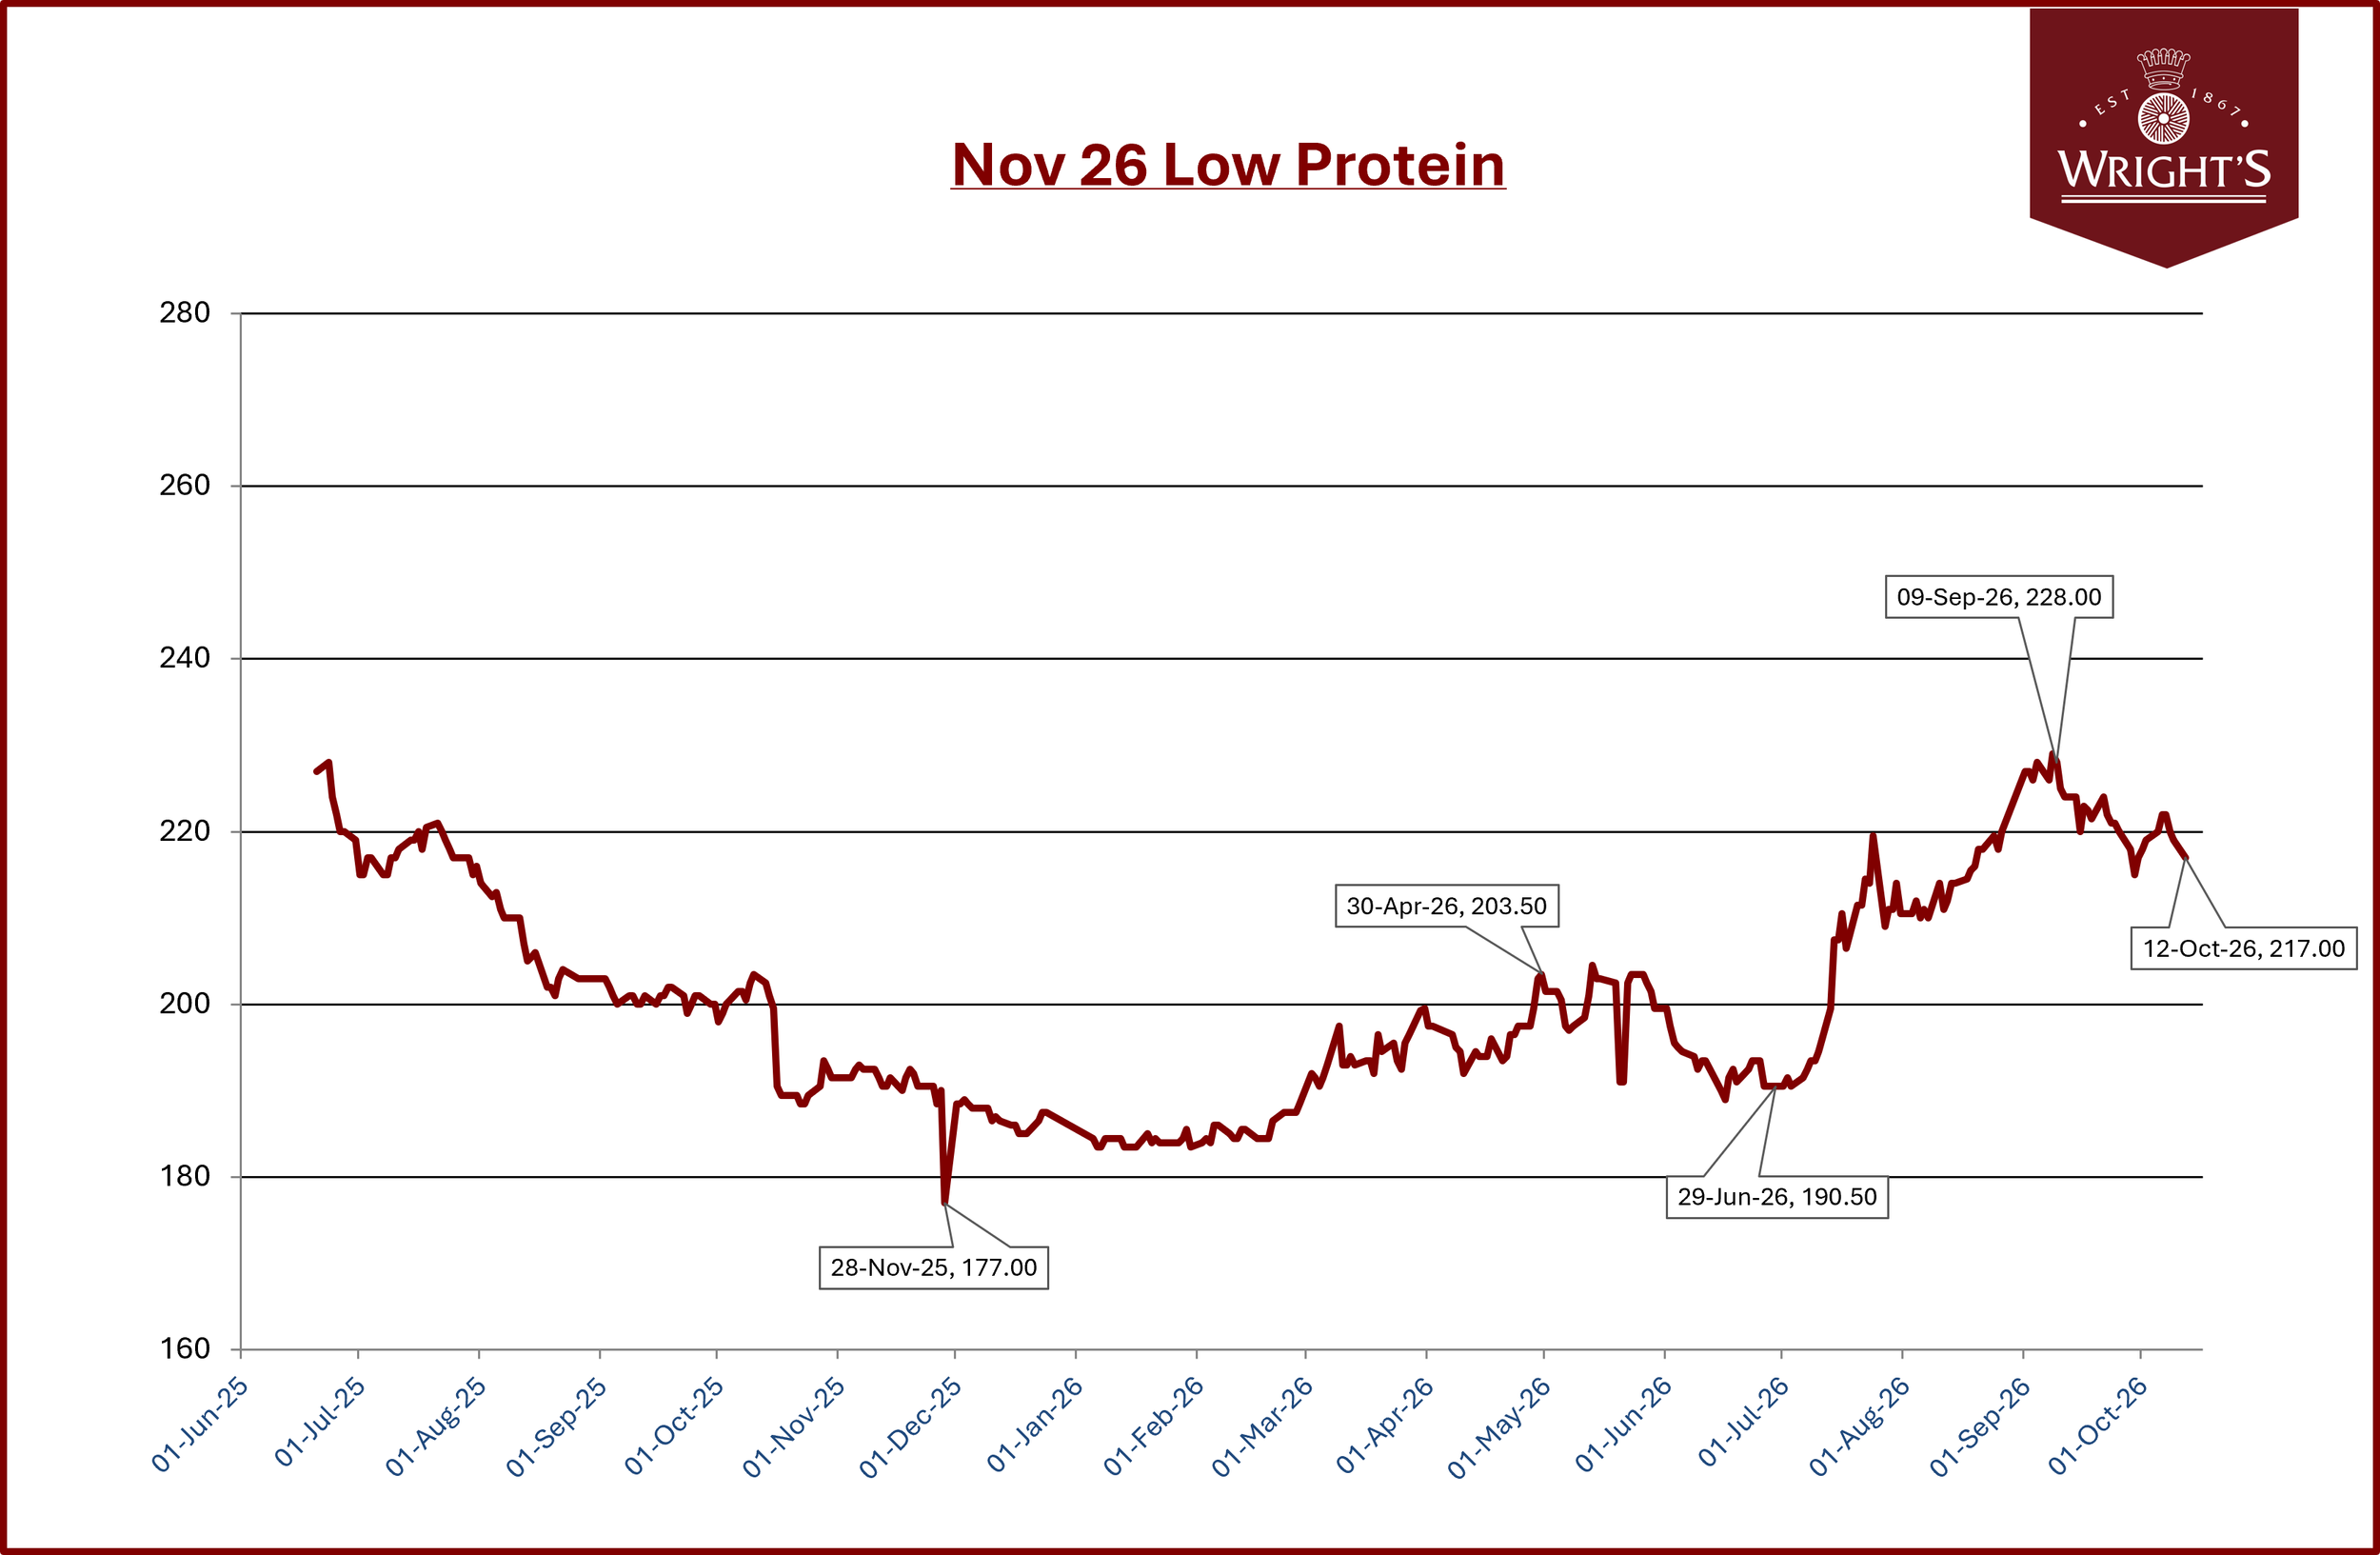
| Group 1's (high protein), delivered | £220/t | £223/t | +£3 |
| Hard & Softs (milling), delivered | £217/t | £219/t | +£2 |
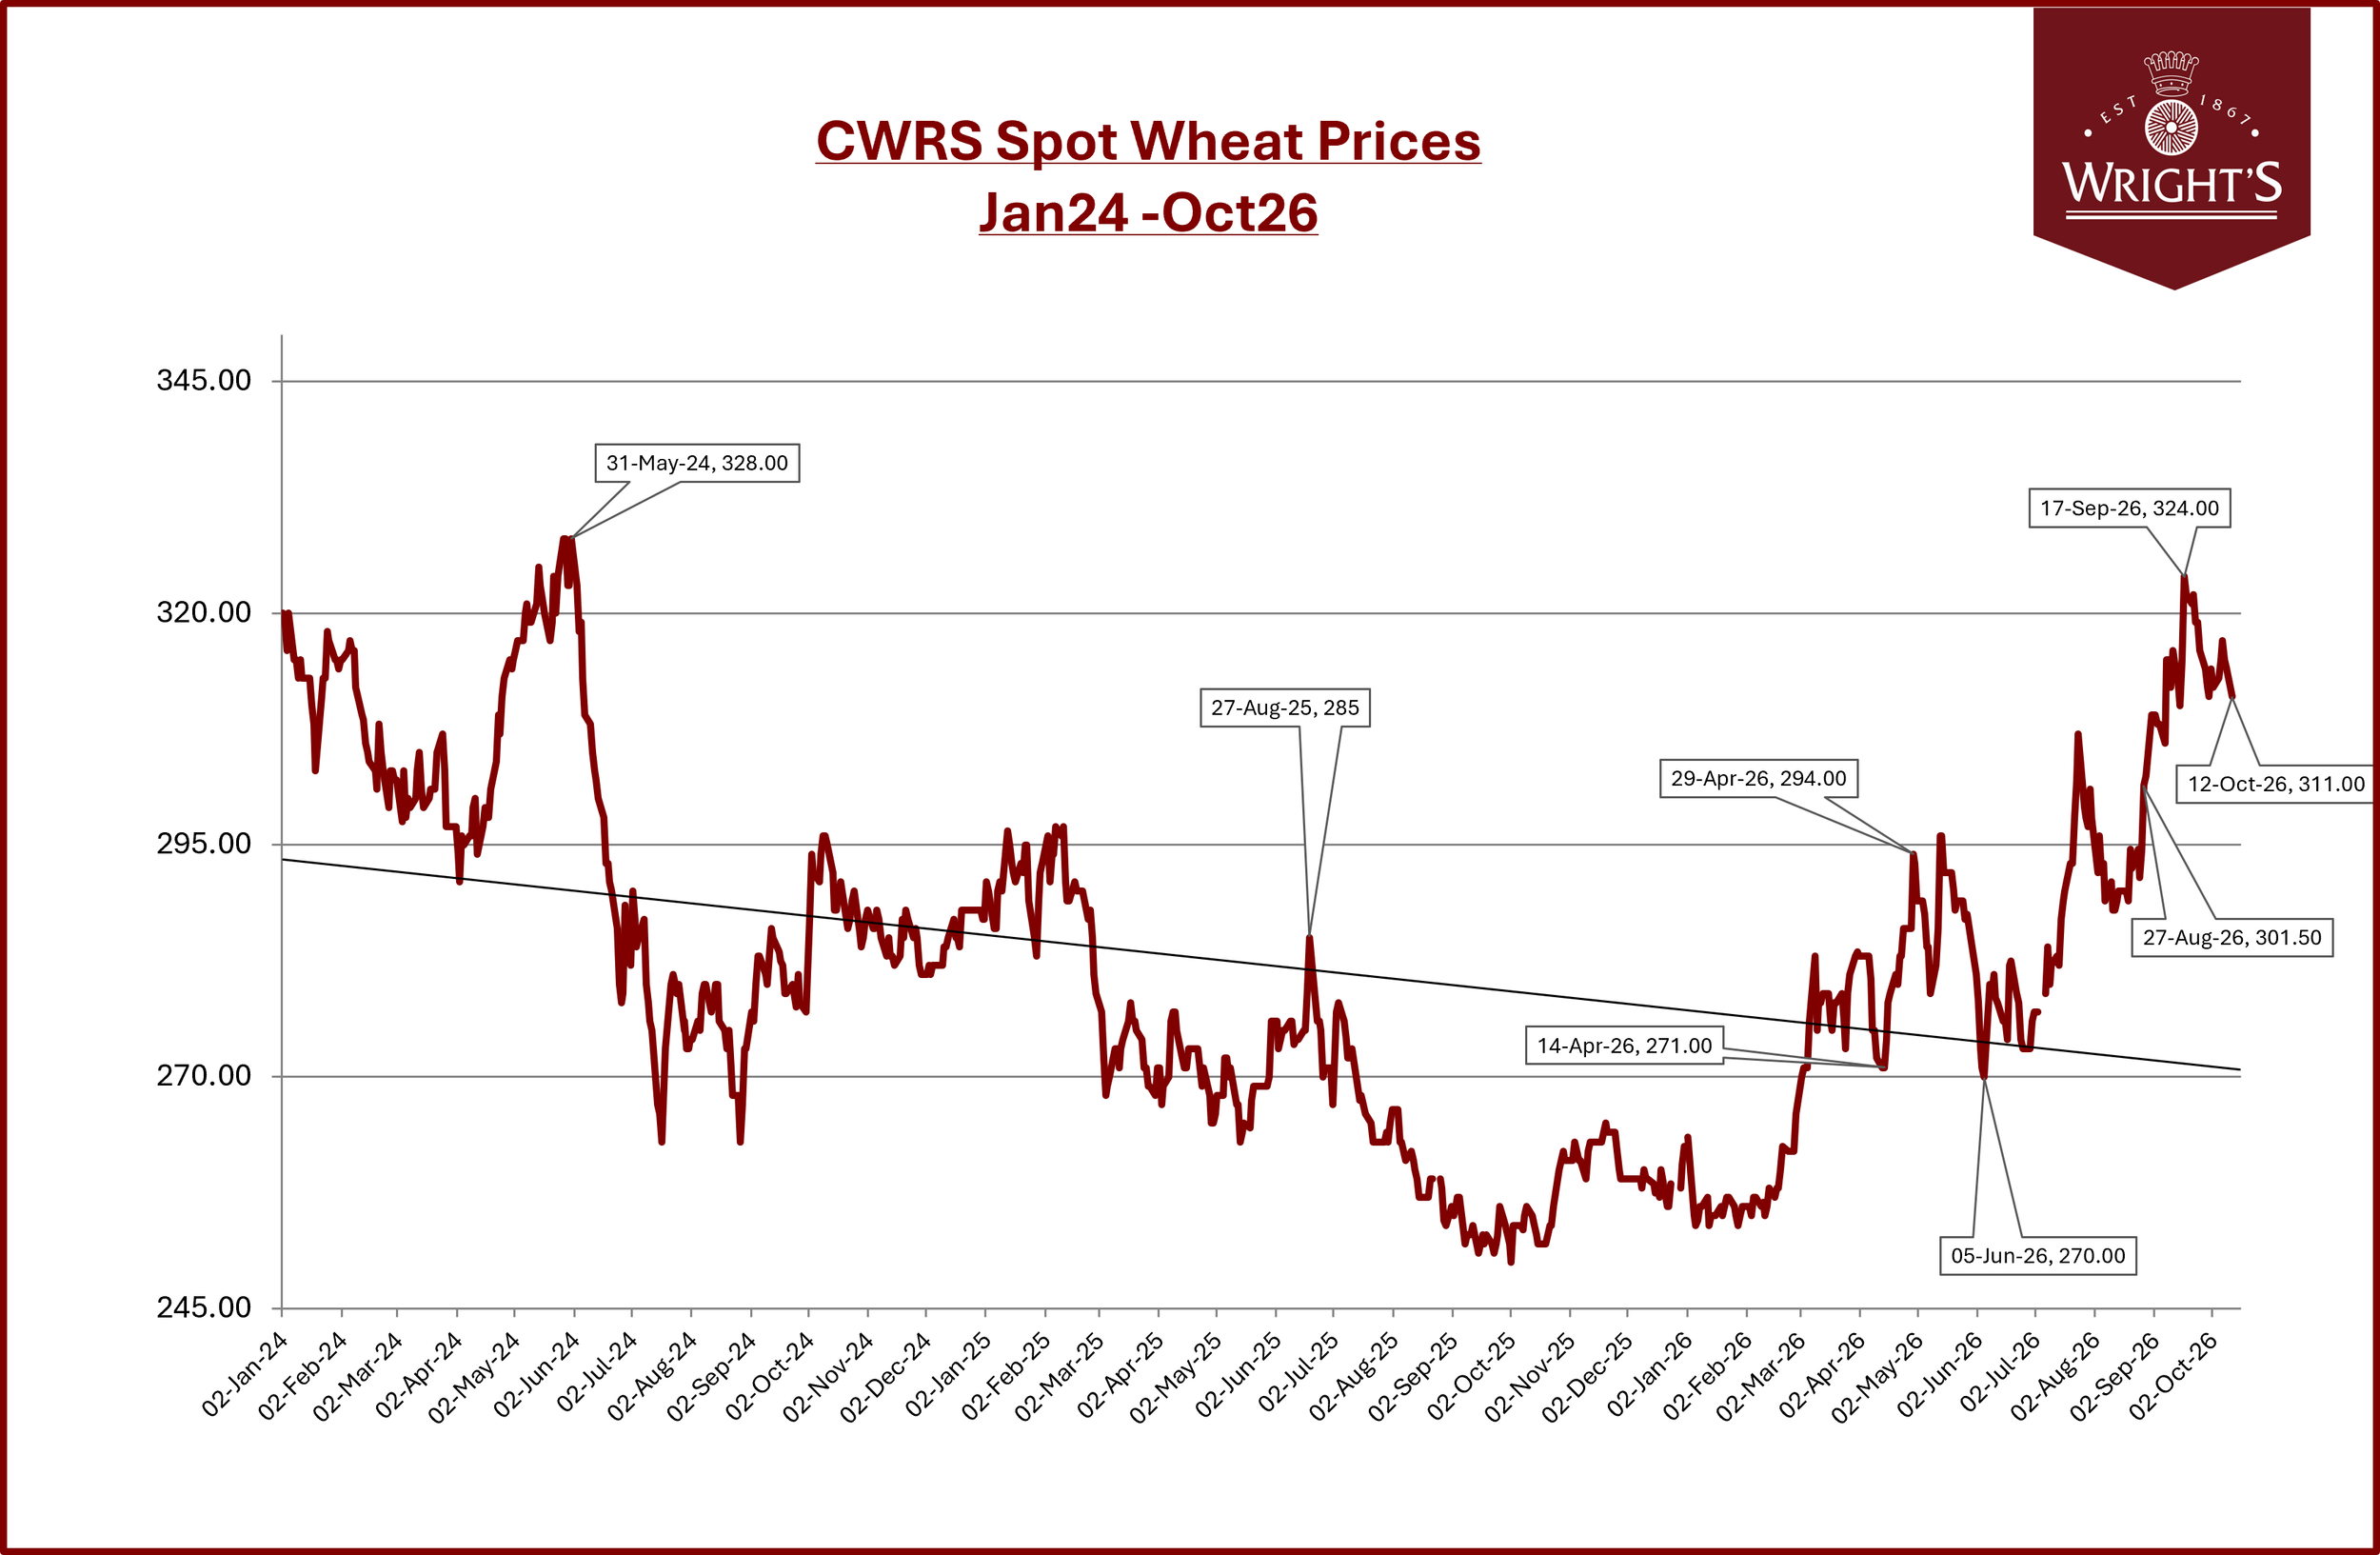
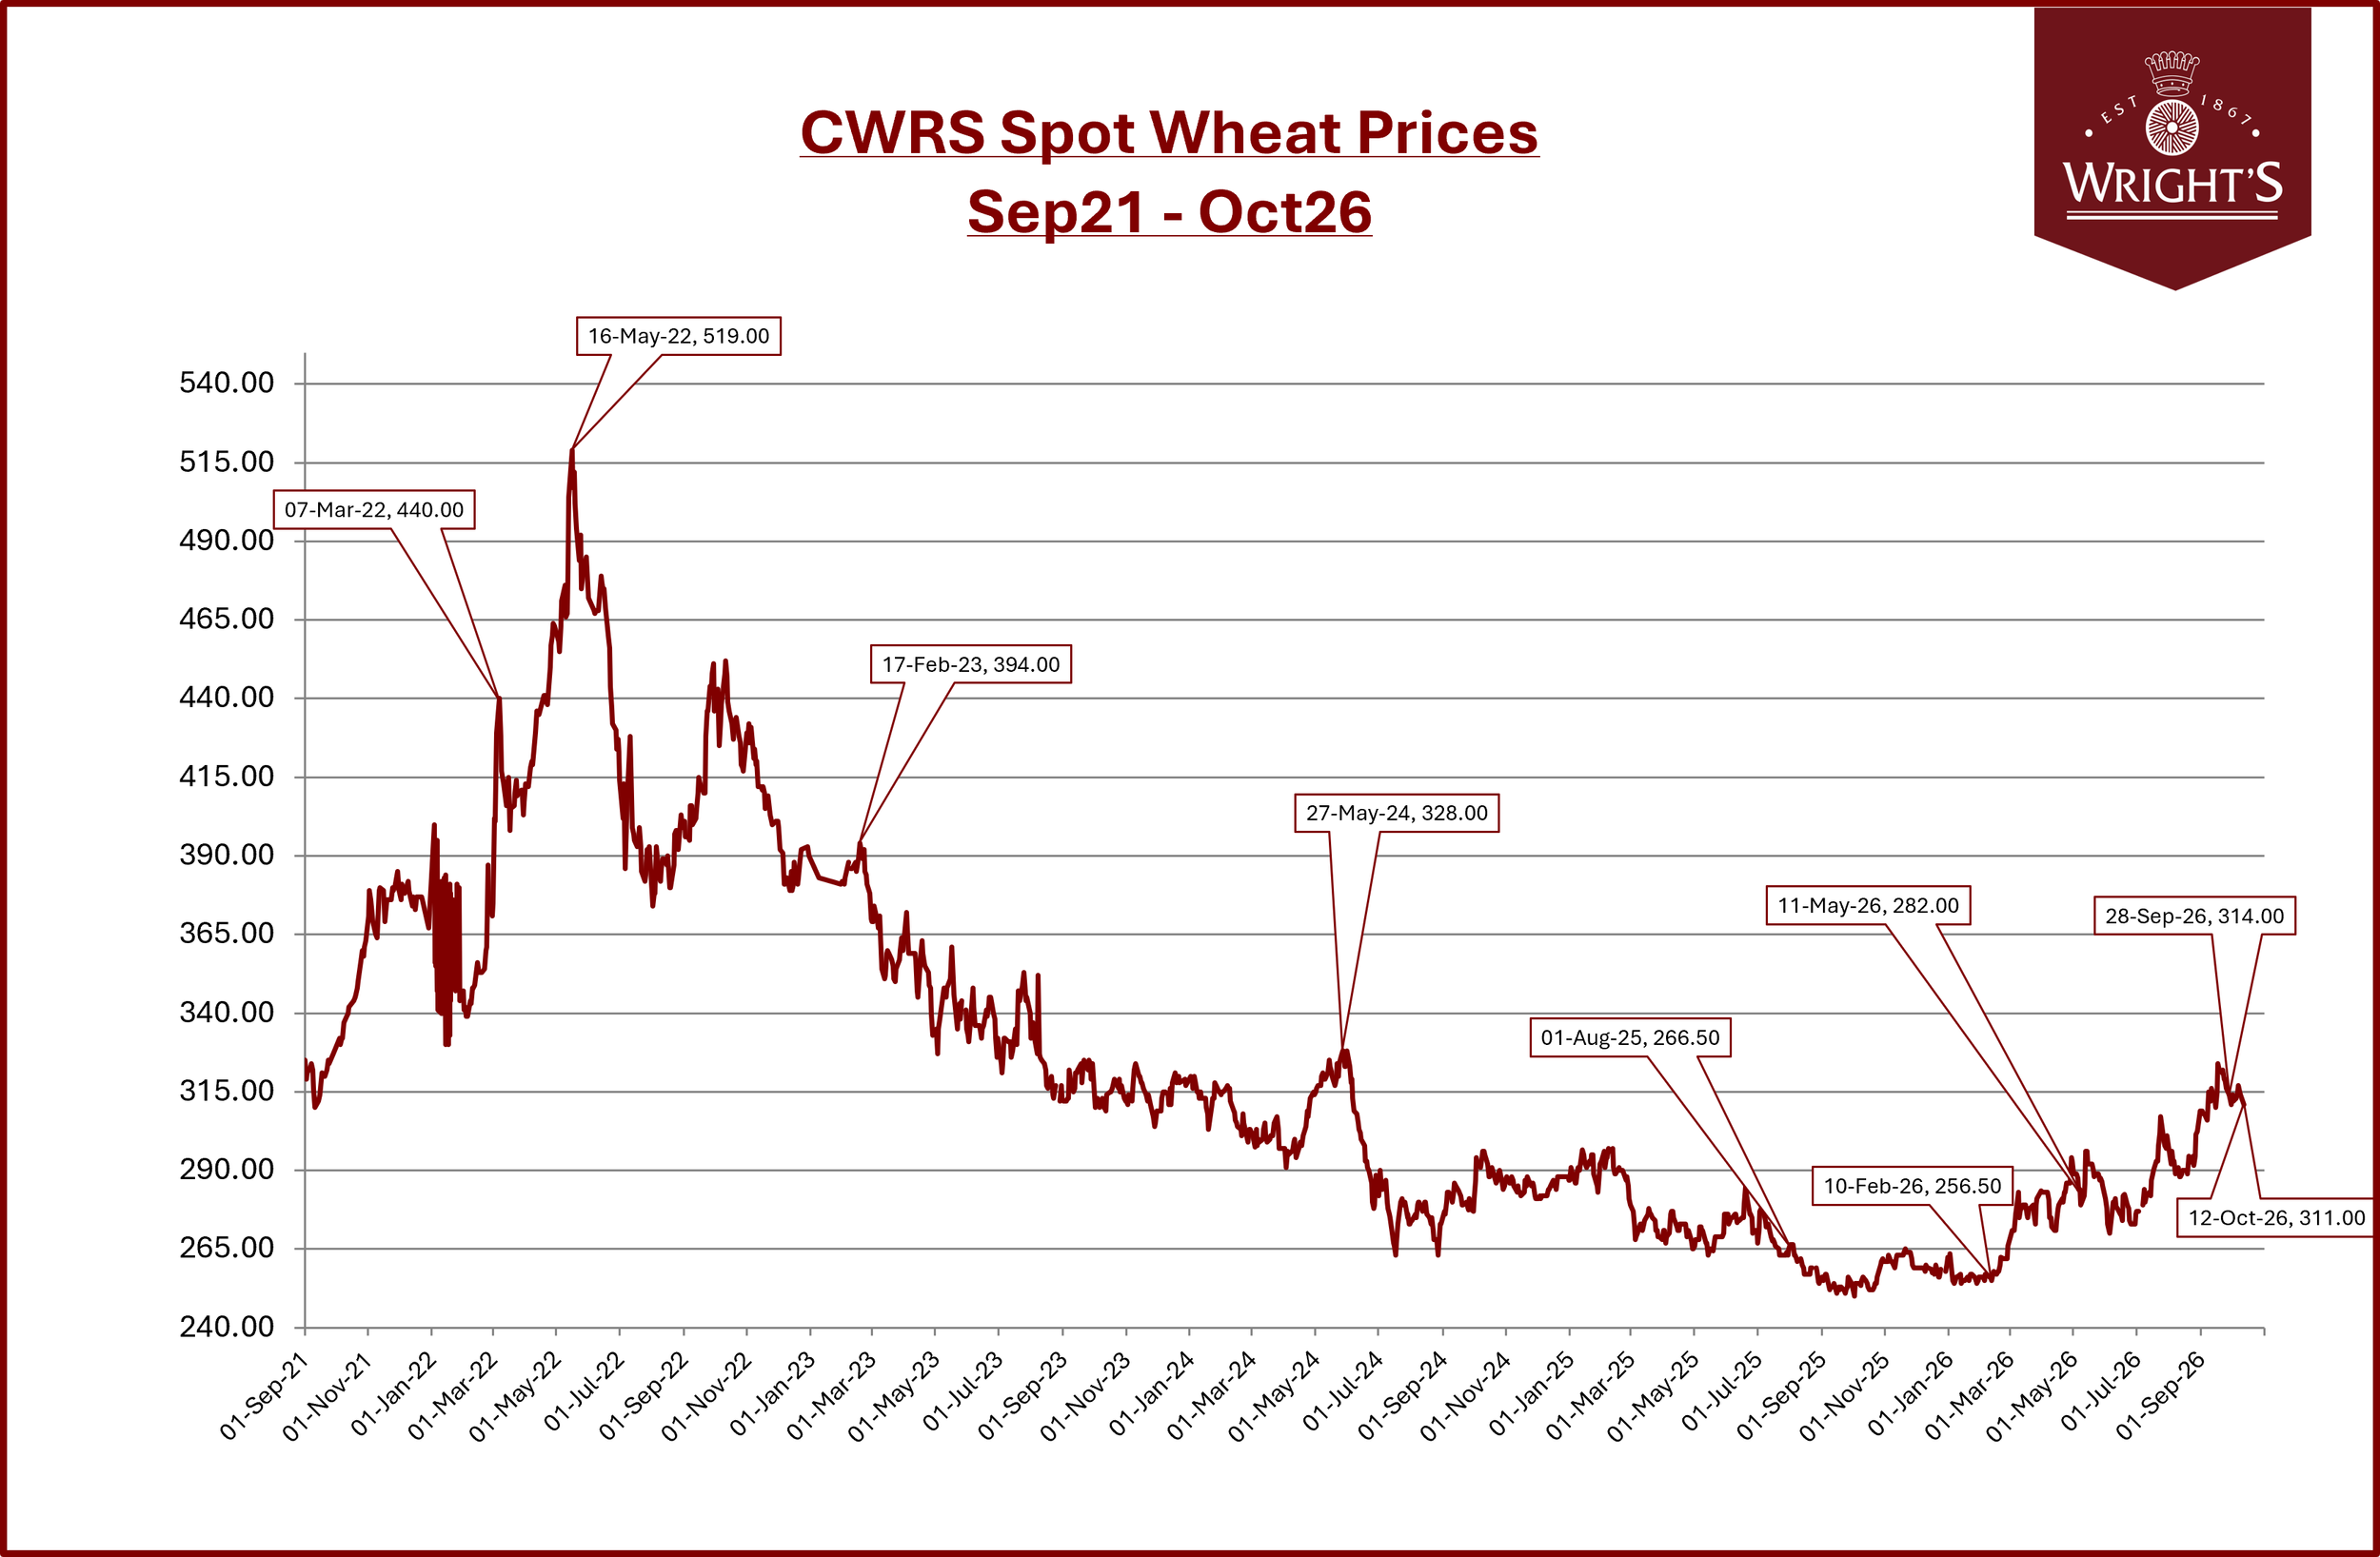
| CWRS 13.5% (Canadian), delivered — spot | £312/t | £314/t | +£2 |
| MATIF milling wheat — Dec-26 | €241.50/t | €242.00/t | +€0.50 (+0.2%) |
| GBP/USD | 1.3205 | 1.3240 | +0.0035 (+0.3%) |
| GBP/EUR | 1.1741 | 1.1800 | +0.0059 (+0.5%) |
Market Drivers
Bullish Factors
Russia-Ukraine shipping squeeze
Disappointing corn harvests
Expected fall in 2026/27 exporter grain stocks
Bearish Factors
Comfortable end-2025/26 major exporter wheat stocks
Russia/Ukraine de-escalation risk
Large southern hemisphere harvests loom
Executive Summary
Wheat markets held a narrow range through the week and finished little changed. Geopolitical tensions in the Black Sea and the Middle East remain the most important market drivers. Early support came from renewed Black Sea risk, as Russian drone strikes on grain-laden vessels off the Bulgarian coast repriced freight and insurance across the route; that was offset into Friday by a bearish USDA report that lifted the US maize crop sharply and, by contrast, capped wheat. UK feed wheat futures were essentially flat, the Nov26 contract closing at £206.00/t on 9 October against £206.25/t a week earlier.
UK Focus
ICE UK feed wheat futures (Nov26, the front month) closed at £206.00/t on 9 October, a shade below £206.25/t the previous Friday. The May27 at £214.75/t and Nov-27 at £204.25/t. The widening gap between the Nov26 and May27 contracts, now around £8.75/t, reflects nearby homes being well bought through to the New Year and stronger forward demand from feed compounders in the north and west. The physical market stayed quiet. Human-consumption demand is subdued while animal-feed demand is relatively firm. Bread-wheat premiums are steady but historically low on limited buying and good harvest quality.
DEFRA has announced a provisional estimate of the 2026 English wheat harvest of 10.8 million tonnes, a slight increase of 0.8% on 2025. This is due to higher yields in all regions except the East of England and the South East (overall yield increased by 2.7% to 7.2 tonnes per hectare (t/ha)). Wheat production increased in all northern and Midlands regions, while the South East, South West, and East of England decreased. Yorkshire and the Humber showed the largest production increase (6.5% since 2025), and the highest yields were seen in the North East (8.4 t/ha).
Global Focus
Paris milling wheat (MATIF, the Euronext European wheat futures market) traded a €233 to 247/t range and settled the Dec26 contract at €242.00/t on 9 October, up about €0.50/t on the week but easing on the day after the USDA report. Chicago wheat (CBOT, the US futures benchmark) softened over the week, pressured by the same report. The October WASDE, released on Friday 9 October, was the week's main event: the USDA raised the US maize yield and lifted US maize ending stocks, a clearly bearish surprise that dragged wheat lower into the weekend. For wheat itself, the report was more balanced: US 2026/27 ending stocks edged up to 740 million bushels, while world ending stocks were trimmed fractionally to about 276.0 Mt; the USDA cut Russia's export forecast to 40.0 Mt from 43.0 Mt.
Russia nonetheless remains the swing supplier: September Baltic shipments hit a record near 1.4 Mt, even as attacks disrupted the route. Ukraine warned that its 2027 winter wheat area could fall by up to 17% on continued export difficulties. Elsewhere, supply is building: Argentina has begun early harvest with a crop near 21.5 Mt, Australia has dodged El Niño with output back around 31 Mt, and the delayed Canadian spring-wheat and durum harvest is advancing amid lingering quality concerns.
Over the weekend, Trump firstly announced the easing of sanctions on Russian diesel, while demanding Ukraine hold elections, before then posting that “both parties have agreed” to pause attacks on each other’s energy infrastructure. President Zelensky told Axios it was “news to me” and Sunday night saw further Russian attacks on Ukrainian energy facilities. The overnight US grain markets remain virtually unchanged.
| Imported wheat, delivered (£/t) | 2 Oct | 9 Oct | Change |
|---|---|---|---|
| German A 13% (breadmaking) | £265/t | £267/t | +£2 |
| German E 14% (premium breadmaking) | £288/t | £290/t | +£2 |
| French min 11% | £282/t | £282/t | — |
| CWRS 13.5% (Canadian) | £312/t | £314/t | +£2 |